guide
CD early-withdrawal penalty
Understand when a penalty can exceed earned interest and reduce principal.
Free certificate of deposit calculator
Estimate a certificate of deposit’s maturity value and interest earnings.
First CD offer
Opening depositInterest
Educational estimate. Excludes taxes, fees, and early-withdrawal penalties.
Make the estimate useful
Use your calculated result without creating an account. Files and saved scenarios stay with you.
Save one set of assumptions for this calculator. It remains on this device until you remove it. Avoid saving on a shared device. This is separate from analytics consent.
The link contains the displayed summary and financial results. Anyone with it can read them. It does not include form inputs or the full projection, and is not encrypted. Only share information you are comfortable disclosing.
A is kept only while this page is open. Compare the assumptions below; different timelines or modes may answer different questions.
| Detail | Scenario A | Latest result B |
|---|
To compare two CDs, use “Compare another CD” above. The CSV includes both offers when enabled. A shared snapshot contains the first offer only.
Different terms lock your money for different lengths of time. A larger maturity value does not by itself make an offer a better fit.
Check penalties, minimum deposits, renewal rules, and insurance coverage in each institution's disclosure.
| Offer | APY | Term | Interest | Maturity value |
|---|
The first offer is shown at opening, each full year, and maturity.
| Milestone | Balance | Interest earned |
|---|
Understand the estimate
Use this CD calculator to estimate a certificate of deposit's maturity value and interest earnings from one opening deposit, APY, and term in months. Compare two CD offers side by side and export the result without sending your numbers to a server.
The calculator treats the advertised APY as the effective annual return, including compounding. For a term measured in months, it uses maturity value = deposit × (1 + APY)^(months / 12). Interest earned is the maturity value minus the opening deposit.
How to read the result: maturity value is the opening deposit plus estimated interest at the end of the selected term. When comparing offers, consider both the interest difference and how long each offer restricts access to the same deposit.
Enter the disclosed APY: it already includes the account’s compounding assumptions. Do not enter a nominal interest rate or compound the APY again. See how CD APY is calculated and the CD interest calculation formula.
Assumptions and limits: Most standard CDs accept one opening deposit and hold it until maturity. This estimate assumes the APY stays fixed and all interest remains in the CD. It excludes taxes, fees, early-withdrawal penalties, promotional conditions, callable or brokered CDs, and institution-specific rounding.
A CD usually restricts access to the money for a stated term, and withdrawing early may trigger a penalty. Compare the term, APY, minimum deposit, penalty, renewal rules, and insurance coverage in the institution's disclosure before opening an account. Read the Consumer Financial Protection Bureau's CD overview.
Review the CD maturity formula and model limits or learn how APY differs from a nominal interest rate. Need recurring deposits instead? Use the savings goal calculator. For a general growth projection, use the compound interest calculator with regular contributions.
Worked example
Enter a $10,000 opening deposit, 4% APY, and a 12-month term. With the interest left in the account, the estimated maturity value is $10,400 and the estimated interest is $400.
Try this example in the calculatorStarting from an interest rate rather than APY? Read CD APY explained before entering the percentage. APY already includes its disclosed compounding effect.
Common questions
It is the opening deposit plus the estimated interest accumulated through the end of the stated term.
APY expresses the effective annual yield after compounding. A nominal interest rate may not include the effect of compounding.
Yes. Enable Compare another CD to use the same opening deposit with a different APY or term. Compare maturity value and interest, then check each institution’s penalties, minimums, and renewal rules.
No. Penalties vary by institution and product. Review the account disclosure before opening or closing a CD.
This calculator models a standard CD funded with one opening deposit. Use the savings goal or compound interest calculator for recurring deposits.
No. A longer term can produce a larger balance while restricting access to the money for more time. Compare term, penalties, minimums, renewal rules, and insurance coverage.
How taxes and inflation change the purchasing power of interest. The calculator result is before both adjustments.
Independent tools. Shared progress.
Managing your financial future shouldn't require expensive software or complicated spreadsheets.
That's why I'm building simple, accessible financial tools to help people plan their savings and understand compound growth.
Our calculators are completely free. If you find them useful, purchasing our $15 Savings & Growth Workbook gives you more powerful planning tools while supporting the development of new free resources.
Explore the workbook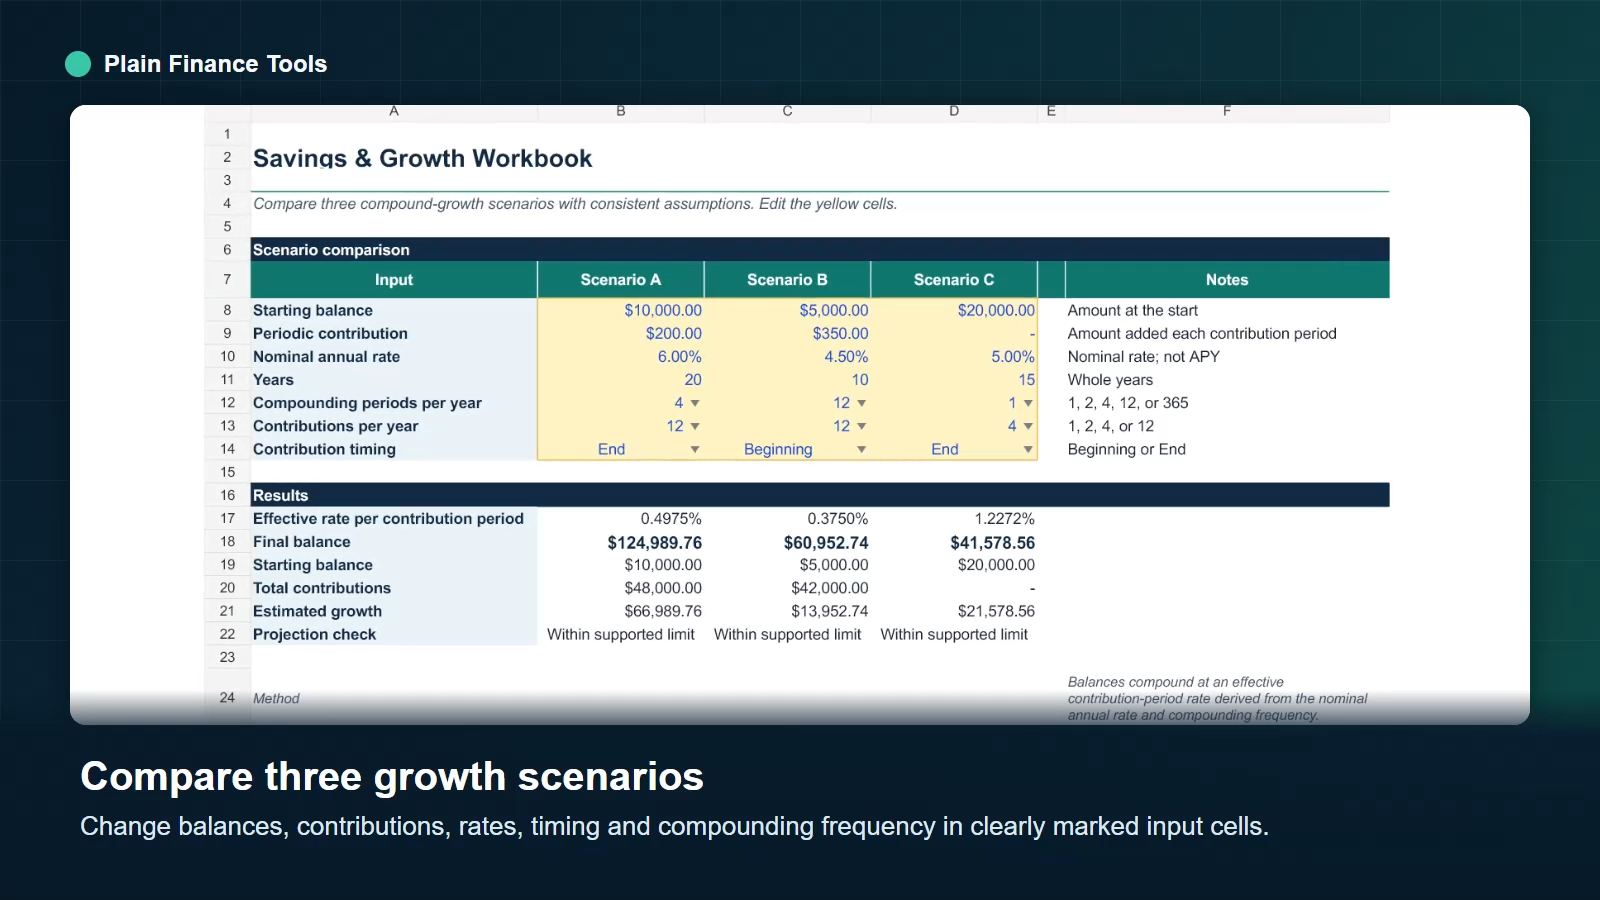 Compare scenarios. Keep your plan.